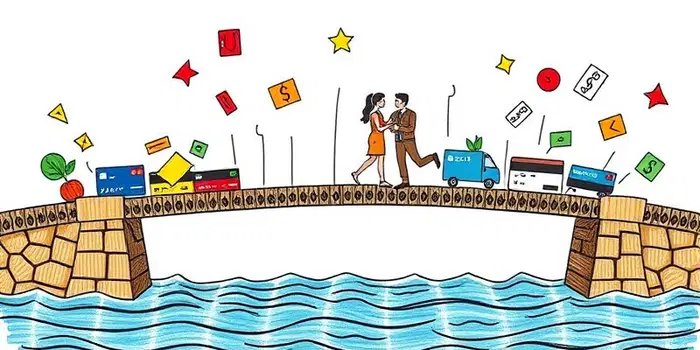
Too often, credit is seen merely as a borrowing tool rather than a powerful financial infrastructure asset that underpins access to essential services. A strong credit profile can unlock housing, vehicles, insurance, utilities, and even employment screenings, while a damaged score can raise costs and limit options just when resilience matters most.
Credit goes beyond approving loans. It shapes the access to borrowing options, influences controlling credit costs proactively, undergirds maintaining borrowing capacity before needed, and reflects assessing your overall credit health. Thinking of credit as infrastructure shifts the focus from short-term borrowing to long-term resilience.
Credit access determines approval. Credit cost sets your rates, fees, and premiums. Credit resilience measures your emergency borrowing flexibility without debt traps. Credit health gauges payment history, balances, mix, and report accuracy.
The Federal Reserve Bank of New York reports that U.S. household debt stood at $18.771 trillion at the end of June 2026, slightly down from Q1 but up $4.6 trillion since 2019. Non-housing balances rose by $48 billion, while mortgage debt declined by $74 billion. Credit-card and auto-loan balances climbed by 1.7%, and student-loan balances dipped by $7 billion.
Delinquency rates remain relatively stable at 4.7%, though student-loan delinquencies climbed to 10.6%. Aggregate figures mask the fact that debt burdens vary widely by age, income, credit score, and loan type.
Maintaining a robust credit profile shapes the affordability and availability of future choices. It can improve everything from mortgage pricing to car financing and emergency liquidity.
Consider this illustrative example: On a $300,000, 30-year fixed-rate mortgage, a 1-percentage-point interest-rate differential can raise your monthly payment by about $190 and add tens of thousands of dollars in interest over the life of the loan.
Choosing a longer loan term to lower payments can increase total interest paid and leave you vulnerable if expenses spike unexpectedly. Balancing cost and resilience ensures you can handle emergencies without becoming trapped in unaffordable debt.
A credit score is a statistical prediction of repayment risk, not a measure of character or wealth. Major models include FICO and VantageScore, each with varying versions and industry-specific algorithms. As a result, you may have multiple scores that differ across bureaus and lenders.
Key scoring factors typically include payment history, credit utilization, length of credit history, new inquiries, and credit mix. The importance of each factor varies by model and individual profile.
Credit utilization measures the share of available revolving credit you’re using. It may be reported as overall utilization (total balances divided by total limits) or per-card utilization (individual balance divided by that card’s limit). High utilization can harm your score even if you pay on time.
Practical tips:
Remember, paying in full by the due date builds payment history without incurring interest charges.
Building and preserving creditworthiness is an ongoing process. Adopting disciplined habits today safeguards your borrowing capacity for tomorrow’s needs.
Beyond these core practices, maintain an emergency fund to reduce overreliance on credit. View credit as a complement to savings, not a substitute. By treating credit as strategic infrastructure—rather than a quick fix—you build long-term financial stability and resilience.
Future-proofing your finances starts now. Cultivate strong credit, manage risks thoughtfully, and ensure you’re prepared for life’s unpredictable challenges.
References